Use recent comparable sales to see which features buyers reward, adjusting for size, condition, location, and sale timing. Compare your property’s asking price and valuation with local sales to spot credible value gaps, then subtract purchase, renovation, and holding costs. Prioritize safety, maintenance, and functional upgrades that address buyer concerns. Get multiple contractor bids, check permits, and include a contingency before committing. Revalue after work using consistent comparables; the steps below show how to assess returns and refine your plan.
Key Takeaways
- Compare recent sales of similar nearby homes to identify features that buyers value and where your property falls short.
- Check asking prices against comparable sales and assessed values, adjusting for differences in size, condition, location, and sale date.
- Prioritize safety, maintenance, and functional upgrades that address valuation gaps and match local buyer preferences.
- Estimate renovation costs using multiple contractor bids, permit requirements, and a contingency; pursue projects only when expected gains justify total investment.
- Compare consistent pre- and post-renovation valuations with market trends and actual costs to measure returns and guide future decisions.
Compare Local Sales to Find Buyer Priorities
What’re buyers paying a premium for in your area? Compare recent sales of similar homes to see which features consistently command higher prices. Track sale price per square foot, days on market, and listing-to-sale price ratios across properties with updated kitchens, extra bathrooms, energy-efficient systems, or usable outdoor space.
Compare similar recent sales to see which home features command a premium and how quickly buyers act.
Adjust for location, size, and condition so you don’t mistake a neighborhood advantage for a renovation premium.
These comparisons reveal Buyer priorities through actual purchasing behavior, not assumptions. Look for repeat patterns across several transactions, then check whether the premium holds in different price ranges.
Market trends can shift quickly, so favor recent sales and note seasonal changes or rising inventory. If homes with a particular feature sell faster and closer to asking price, you’ve found a signal worth investigating before choosing upgrades for your property.
Use Property Valuation to Find Value Gaps
Once you’ve identified features buyers value, use property valuations to spot homes priced below their potential. Compare each property’s asking price with its estimated market value, recent comparable sales, and assessed value. Don’t treat one figure as definitive; check how the valuation accounts for size, condition, location, and sale timing.
Then test the gap against Market trends. If comparable prices are rising, a discount may signal an opportunity—or outdated data. If prices are flat or falling, build in a wider margin for uncertainty.
Review Neighborhood dynamics, too: shifts in demand, inventory, and buyer activity can explain why a home trades below nearby properties.
Estimate your likely resale value using current evidence, then subtract acquisition costs and planned expenses. A credible value gap should remain after those deductions, not depend on optimistic assumptions.
Match Renovations to the Home’s Weak Points
After confirming a credible value gap, match renovations to the features holding the home back. Compare the valuation report, inspection findings, and recent comparable sales to pinpoint what buyers discount.
If similar homes command premiums for updated kitchens, dated cabinets or poor layouts may be limiting yours. If listings highlight low utility costs, inefficient windows or aging HVAC could weaken your position.
Prioritize fixes that address measurable buyer concerns, not upgrades you simply prefer. Design aesthetics matter when finishes look dated beside competing properties, but align choices with neighborhood standards and buyer expectations.
Energy efficiency can improve appeal where utility costs influence demand; check local listing data for evidence. Address safety, deferred maintenance, and functional problems before cosmetic details.
Your renovation plan should respond to the home’s specific weaknesses and the features buyers reward in that market.
Estimate Renovation Costs and Resale Potential
Price each renovation using contractor bids and current material costs, then compare the total with your budget.
To assess resale potential, use recent comparable sales to estimate the property’s post-renovation value.
Your projected value gain should exceed renovation costs, carrying expenses, and a margin for risk.
Estimate Renovation Costs
To assess a property’s value-add potential, estimate renovation costs against the resale value of comparable homes—not a seller’s optimistic projection. Start with a room-by-room scope, separating essential repairs from upgrades that may improve buyer appeal.
Price labor, permits, disposal, and materials using current local rates. Materials selection can shift your budget substantially, so compare durable options at different price points.
Seek multiple Contractor bidding proposals based on the same written specifications, then check what each quote excludes. Verify contractor credentials and confirm timelines, payment schedules, and warranty terms before relying on an estimate.
Add a contingency—often 10% to 20%—for hidden damage, code requirements, or price changes. Use inspection findings and recent project costs in your market to test assumptions.
Track each line item so you can revise the budget as new information emerges.
Assess Resale Potential
How much could the renovated property realistically sell for? Start with recent closed sales, not optimistic asking prices. Compare renovated homes with similar size, layout, age, and location, then adjust for features buyers actually value.
Market trends matter: track sale-to-list ratios, days on market, inventory, and price changes to see whether demand supports your target.
Neighborhood dynamics can shift resale potential block by block. Check school zones, transit access, planned development, and competing listings. Ask local agents which upgrades attract offers and which rarely recover their cost.
Next, subtract your purchase price, renovation budget, financing, carrying costs, and selling expenses from the likely sale price. Model conservative, expected, and upside outcomes, allowing for overruns and market softening.
If the conservative case leaves too little margin, revise the scope or negotiate a lower acquisition price before committing.
Check Permits, Quotes, and Project Risks
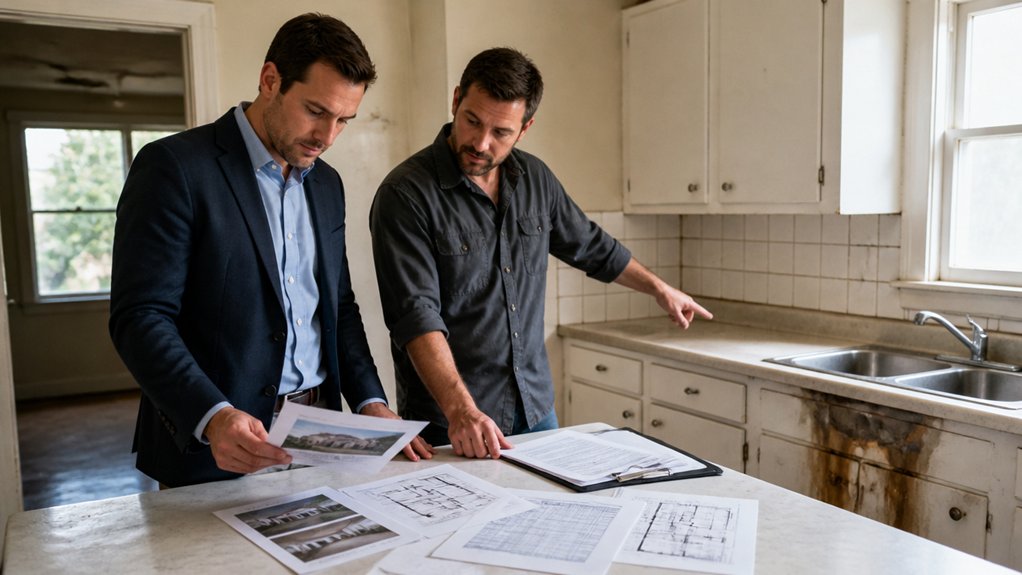
Before treating a valuation gap as a renovation opportunity, verify that the work is permitted, priced, and feasible. Check Building permits with your local authority, including zoning limits, inspection requirements, and approval timelines. Unpermitted work can delay a sale, trigger costly corrections, or reduce buyer confidence.
Get itemized contractor quotes based on the same scope so you can compare labor, materials, exclusions, and schedules. Test each estimate against recent local costs, not broad averages, and include a contingency for hidden conditions such as outdated wiring or water damage.
Then assess whether the project fits your financing, cash reserves, and holding period.
You should also weigh contractor availability, supply delays, insurance, and disruption risks. If approvals or pricing remain uncertain, treat the projected upside as provisional.
A realistic risk-adjusted budget helps you decide whether the opportunity merits further due diligence before committing.
Revalue the Property and Measure the Results
Once renovations are complete, schedule a new valuation to capture the property’s current market position.
Compare it with your pre-project valuation to isolate the value added.
Then measure ROI against total costs to see whether the improvements delivered.
Schedule a New Valuation
After renovations are complete, schedule a new valuation to measure how the work has changed the property’s market value. Choose a qualified appraiser who understands your local market and the improvements you’ve made. Provide permits, invoices, plans, and details on upgraded materials so the appraiser can assess the work accurately.
Request the valuation when the project is fully finished and the property is ready for inspection; incomplete work can distort the result. Consider market timing, too: seasonal demand and recent sales can influence an estimate, so ask how current conditions affect the analysis.
A credible valuation gives you a defensible figure for financing, sale planning, or expert negotiation. Confirm the report’s effective date, valuation method, and assumptions, then keep it with your renovation records. You’ll have a reliable basis for your next decision.
Compare Before and After
How much value did the renovation actually add? Compare your updated valuation with the pre-renovation figure to see how the property’s market position changed.
Ask your valuer to assess the home using the same valuation methods and, where possible, comparable sales from the same area. This consistency helps you isolate changes linked to the renovation rather than shifts in assumptions or data.
Review the evidence behind both estimates: recent sale prices, property condition, floor area, and features buyers value locally. Check whether the valuer adjusted for broader property market movements between assessments.
A higher figure may reflect rising local prices as well as improvements, while a flat result could signal that buyers don’t prize the work as expected.
Record the new valuation and key assumptions so you can make informed decisions about future upgrades.
Measure Return on Investment
A new valuation shows the property’s updated market position; measuring return on investment reveals whether the renovation paid off. Compare the new value with your pre-renovation valuation, then subtract renovation costs, financing, permits, and holding expenses to calculate net gain.
Divide that gain by your total investment to find ROI. Include rental income or reduced vacancy if the work improved cash flow; don’t count projected gains as realized returns.
Check comparable sales and market trends to distinguish renovation impact from broader price movement. If local values rose, your uplift may reflect the market, not just upgrades.
Review investment timing, too: delays, seasonal demand, and borrowing costs can change the result. Compare actual performance with your budget and target return.
If ROI falls short, use the valuation and expense breakdown to refine future project scope, pricing, and timing.
Frequently Asked Questions
How Often Should Property Valuations Be Updated?
Like the tides, property values shift with the market. Update your valuation at least annually, and sooner when you’re buying, selling, refinancing, or planning major work.
For effective Market timing, review it quarterly using recent comparable sales, rental trends, and local supply data.
Before setting Renovation budgeting, obtain a fresh assessment so you don’t rely on stale figures.
You’ll make stronger decisions when you revisit valuations after significant neighborhood changes or interest-rate moves.
Which Valuation Methods Are Commonly Used for Residential Properties?
You’ll commonly see three methods for valuing residential properties. The sales comparison approach uses recent sales of similar homes. Comparative analysis adjusts for differences such as size, condition, and location.
The income approach estimates value from rental income, which suits investment properties.
The cost approach adds land value to estimated replacement costs, minus depreciation.
Your choice depends on the property and available data. Check market trends and local comparable sales to ground your estimate in current conditions.
Who Is Qualified to Provide an Independent Property Valuation?
You’ll typically need a licensed or certified appraiser with relevant experience in your property type and local market.
For a credible Property appraisal, check their credentials, independence, professional liability coverage, and familiarity with comparable sales and current market data.
Ask whether they follow recognized Valuation standards, such as those required by local regulators or professional bodies.
You can also request a sample report, confirm the scope and fee upfront, and verify they’ve no conflicts of interest.
How Do Interest Rates Affect Property Valuations?
Interest rates affect property valuations by changing what buyers can afford and what investors expect to earn. When rates rise, your borrowing costs increase, often shrinking buyer demand and putting downward pressure on prices.
Lower rates can improve affordability and support higher valuations.
Track Interest rate trends alongside local sales, rents, and yields; Market fluctuation can obscure the underlying direction.
Compare recent transactions and financing assumptions to judge whether a valuation reflects lasting fundamentals or short-term rate shifts.
Are Online Property Valuation Estimates Reliable?
Online property estimates are a useful compass, not a crystal ball. You can use them for a quick starting point, but accuracy varies with local data, recent comparable sales, and your property’s condition.
Check market trends and verify estimates against nearby transactions. Most algorithms can’t assess layout, deferred maintenance, or upgrades firsthand, so factor in renovation costs separately.
Before making an offer or setting a budget, compare multiple estimates and ask a local appraiser or agent to review the numbers.