To invest wisely in residential property, match each purchase to your goals, risk tolerance, budget, and preferred level of involvement. Compare recent sales and realistic rents to assess value, then calculate net yield after expenses and test returns against vacancies or rising rates. Budget for taxes, fees, repairs, and reserves before committing. Check the home’s condition, legal compliance, and environmental risks. Set a competitive rent, screen tenants carefully, and manage maintenance to protect income and value. The guide ahead explains how to make each decision confidently.
Key Takeaways
- Define whether your priority is rental income, long-term appreciation, or a balance, then choose a property and location that fit your budget and risk tolerance.
- Estimate value using comparable sales and realistic rental evidence; calculate gross and net yields, allowing for vacancy, expenses, and rent reductions.
- Budget for deposits, taxes, legal and lender fees, repairs, and reserves; stress-test mortgage payments against higher rates and lower rental income.
- Commission a qualified survey and verify planning, safety, energy, environmental, and insurance requirements before committing to purchase.
- Set rent using local market evidence, screen tenants, use a compliant tenancy agreement, and maintain the property promptly.
Choose a Residential Investment Property That Fits Your Goals
Before comparing properties, decide what you want your investment to achieve: steady rental income, long-term growth, or a balance of both. Your priorities should shape the location, property type, and level of involvement you’re willing to accept.
If you value dependable income, consider areas with established employers, transport links, and consistent tenant demand. If you’re targeting appreciation, assess neighborhoods with planned infrastructure, population growth, or signs of regeneration.
Market trends can reveal opportunities, but don’t let short-term excitement override your financial plan. Compare likely risks, including vacancies, maintenance demands, and changing local conditions, against your capacity to manage them.
Your investment strategies should also reflect your timeline, available capital, and tolerance for uncertainty. Choose a property that supports your objectives and fits your resources, rather than chasing a popular area or a fashionable building.
Check the Property’s Value and Rental Yield
Once you’ve identified a property that fits your goals, test whether its price and rental potential make financial sense. Compare recent sales of similar homes, adjusting for location, condition, size, and features. Use appraisal methods such as comparable-sales analysis and, where appropriate, an income-based valuation to challenge the asking price.
Check Market trends in the neighbourhood, including sale prices, vacancy levels, and tenant demand; broad averages can conceal local shifts.
Estimate achievable rent using current listings and evidence from letting agents, not optimistic projections. Calculate gross rental yield by dividing annual rent by the purchase price, then assess likely ongoing operating expenses to understand net yield.
Stress-test your figures against modest rent reductions or periods without tenants. If the numbers depend on unusually high rents or rapid appreciation, negotiate firmly or walk away.
Budget for Purchase Costs and Financing
A property’s asking price is only part of the investment, so calculate the full cash required to complete the purchase and keep it financially viable. Add legal fees, transfer taxes, lender charges, valuation costs, and any applicable broker fees.
Check local Tax implications, including rules that affect purchase taxes and deductible financing expenses; a tax professional can clarify your position.
Next, test whether your deposit, mortgage payments, and reserve funds fit your budget. Compare interest rates, loan terms, and fees, then stress-test repayments against rate rises and Market fluctuations that could reduce rental income or resale value.
Don’t rely on optimistic projections: allow for closing costs and keep cash available after completion. A realistic financing plan protects your returns and helps you avoid borrowing beyond what the investment can support.
Check the Home’s Condition, Compliance, and Risks
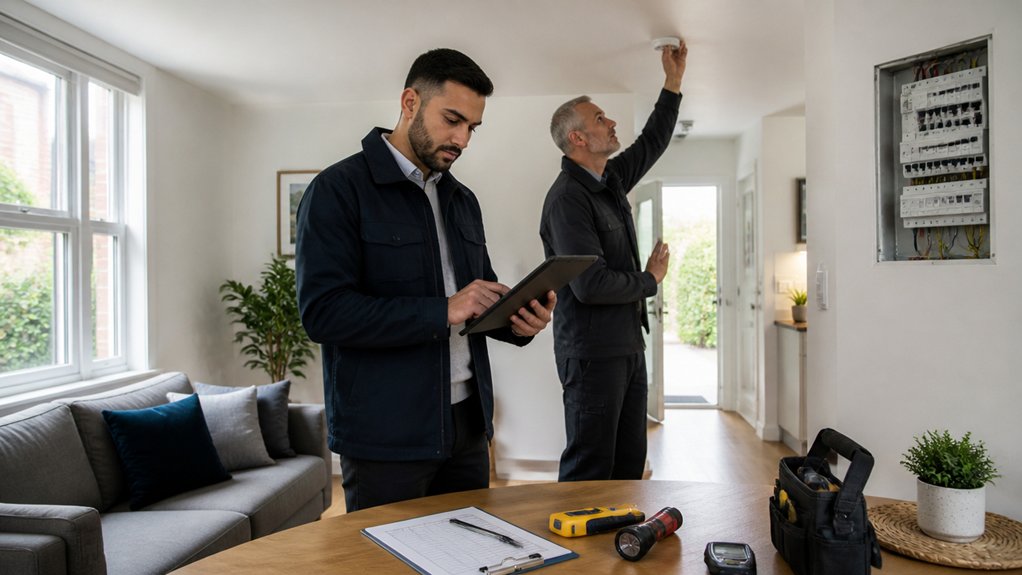
Your financing plan only works if the property’s condition and legal status support the costs you’ve projected. Arrange a thorough Property inspection before you commit, and ask a qualified surveyor to assess the roof, structure, plumbing, wiring, heating, and signs of damp or pests. Use the findings to estimate urgent repairs, future maintenance, and potential disruption; negotiate the price or walk away if the numbers no longer work.
Check Legal compliance separately. Confirm the property’s permitted use, building approvals, safety certificates, energy rating, and any restrictions, such as conservation rules or lease terms. Requirements vary by location, so verify current obligations with the relevant authority or a solicitor rather than relying on the seller’s assurances.
Also review flood, subsidence, contamination, and insurance risks. These checks help you price uncertainty realistically and avoid costly surprises after purchase.
Set the Rent and Find Reliable Tenants
Set rent by comparing recent listings and achieved rents for similar properties in the same area, adjusting for condition, size, amenities, and transport links.
Then weigh Market trends, including seasonal demand, new supply, and local employment, against your target return. A rent that’s too high can prolong vacancies; one that’s too low can weaken your investment.
To find reliable tenants, advertise accurately and respond promptly to enquiries. Ask each applicant for references, proof of income, and consent to appropriate background checks.
Assess affordability consistently rather than relying on instinct, and verify information with previous landlords where possible. Explain your expectations clearly before accepting an application.
Check legal considerations before setting terms: follow local rules on advertising, deposits, discrimination, and tenant screening.
Use a written tenancy agreement that reflects current requirements, and give applicants enough time to review it before signing.
Manage Your Rental Home and Protect Your Returns
Protecting your returns starts with screening tenants carefully, since reliable renters reduce missed payments and costly disputes.
You’ll also preserve your property’s value by scheduling regular maintenance before small defects become expensive repairs.
Together, these practices help you manage risk and sustain rental income.
Screen Tenants Carefully
A reliable tenant can preserve your rental income and reduce costly disputes, so screen every applicant consistently before signing a lease.
Effective Tenant screening starts with clear, lawful criteria applied equally to everyone. Verify each applicant’s identity, income, employment, and rental history, then contact previous landlords to confirm payment habits and lease compliance.
Use Background checks to assess relevant credit and public-record information, following local laws and obtaining required consent. Don’t rely on a single score: weigh documented evidence against your stated standards, and give applicants a fair chance to explain discrepancies.
Keep records of your decisions and communications; consistent documentation helps you demonstrate that your process was objective. Avoid questions or criteria that could discriminate against protected groups.
A careful, consistent review helps you choose someone likely to pay on time, respect the lease, and provide dependable returns.
Maintain the Property Regularly
Regular maintenance helps you preserve rental income by catching small problems before they become expensive repairs. Schedule inspections between tenancies and address leaks, damaged fixtures, and worn seals promptly. A minor plumbing fault can waste water, damage finishes, and lead to costly disputes if you ignore it.
Create a seasonal checklist for heating, ventilation, smoke alarms, gutters, and exterior surfaces. Prioritize utility maintenance, since reliable systems protect residents’ comfort and help prevent emergency callouts.
Keep service records and receipts; they support budgeting, demonstrate responsible management, and help you spot recurring faults.
Maintain gardens and paths to reduce hazards and keep the home appealing. Landscaping upgrades, such as hardy plants or improved drainage, can strengthen curb appeal without adding excessive upkeep.
Respond quickly to tenant reports, communicate clearly, and plan preventive work around occupancy.
Consistent care can support renewals, protect property value, and sustain returns.
Frequently Asked Questions
How Does Property Investment Compare With Stocks and Bonds?
Property investment is a sturdy ship, while stocks and bonds offer different ways to navigate risk. You’ll typically gain rental income and tangible ownership, but face maintenance costs, vacancies, and concentrated exposure.
Stocks can deliver stronger growth yet bring greater Market volatility; bonds usually provide steadier income.
Investment liquidity favors stocks and bonds, which you can generally sell faster than property.
Your choice depends on your goals, time horizon, diversification needs, and tolerance for hands-on management.
What Tax Deductions Can Residential Landlords Claim?
You can generally deduct ordinary, necessary expenses for operating your rental, including mortgage interest, property taxes, insurance, repairs, management fees, utilities, and eligible travel.
You may also claim depreciation on the building, but not the land.
Deduction limits and rules vary by jurisdiction, ownership structure, and whether you actively participate, so keep detailed records and separate improvements from repairs.
Tax credits may apply to qualifying upgrades; consult a tax professional before filing to confirm eligibility and current rules.
Should I Invest Through a Company or as an Individual?
You should choose based on your tax position, financing needs, and risk tolerance.
A company may offer a lower tax rate on retained profits and help separate business assets, but you’ll face extra administration, potential tax when withdrawing profits, and different mortgage terms.
Investing personally is often simpler and may suit you if you value direct ownership and available allowances.
Assess each corporate structure’s costs and personal liability with a qualified tax adviser before deciding.
How Can I Diversify My Property Investment Portfolio?
You can diversify your property investment portfolio by spreading your capital across locations, property types, tenant groups, and investment strategies. Consider residential, commercial, and mixed-use assets, but research demand, costs, and local regulations before committing.
Property diversification can reduce your exposure to a single market downturn, though it won’t eliminate risk.
For effective Portfolio balancing, compare each asset’s income potential, liquidity, financing, and management demands, then adjust your mix to match your goals and risk tolerance.
When Is the Right Time to Sell an Investment Property?
You should sell when the property no longer supports your goals, whether its returns have weakened, major costs loom, or another investment offers better potential.
Could holding on cost you more than selling now? Assess market timing, but don’t rely on perfect forecasts; compare current offers with your expected future returns.
Include emotional considerations, too: separate attachment from evidence.
Review taxes, fees, and reinvestment plans before deciding, so you protect your capital and act with confidence, not impulse.